Skip to content
Artwork for The Noble Update Podcast
BusinessInvesting

The Noble Update Podcast

George Noble

Curating The Latest Deep Dive Investment Insights

georgenoble.substack.com
Play
  • 67 episodes
  • Avg 34 min
  • English
Counted on this page — what you have heard stays on this device, so it is not something the list can be paged by.
  • Today · 8 min

    Billions in Chips Are Sitting in Warehouses Collecting Dust | Bloomberg

    BLACK FRIDAY SPECIAL: $300 OFF THE NOBLE UPDATE. For Black Friday only, the annual plan is $599 instead of $899, and you keep that price for as long as you stay a member. Here’s what you get: * Every new long and short idea I publish, with the full research behind it * Our live subscriber calls, with replays * The NEW Noble Update Portfolio, with every position we hold The offer is for the annual plan only. Claim your spot today: I believe Nvidia is the biggest case of industrial espionage and fraud in the history of the US stock market. The bulls still defend the AI trade by pointing to chip prices, because used GPUs have held their value on both the contract and spot markets. I believe keeping those prices buoyant was one of Jensen Huang's goals all along. There are tens, maybe hundreds of billions of dollars of chips sitting in warehouses collecting dust, and the only real buyers were loss-making, VC-funded startups. Now the bank of AI has federal authorities in the building and its chief loan officer is gone, so the money that funded those buyers stops flowing and the chips have nowhere to go. Tom Keene asked me on Bloomberg if anyone can measure the residual value of the silicon in these data centers the way you can price a used Boeing 737. My answer: You can't. And it's about to get much worse, because those chips will be selling on eBay by the truckload. Check out the full Bloomberg episode with Tom Keene! This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe

    • Transcript
  • Saturday · 3 min

    NVIDIA's biggest bulls just showed you how scared they are

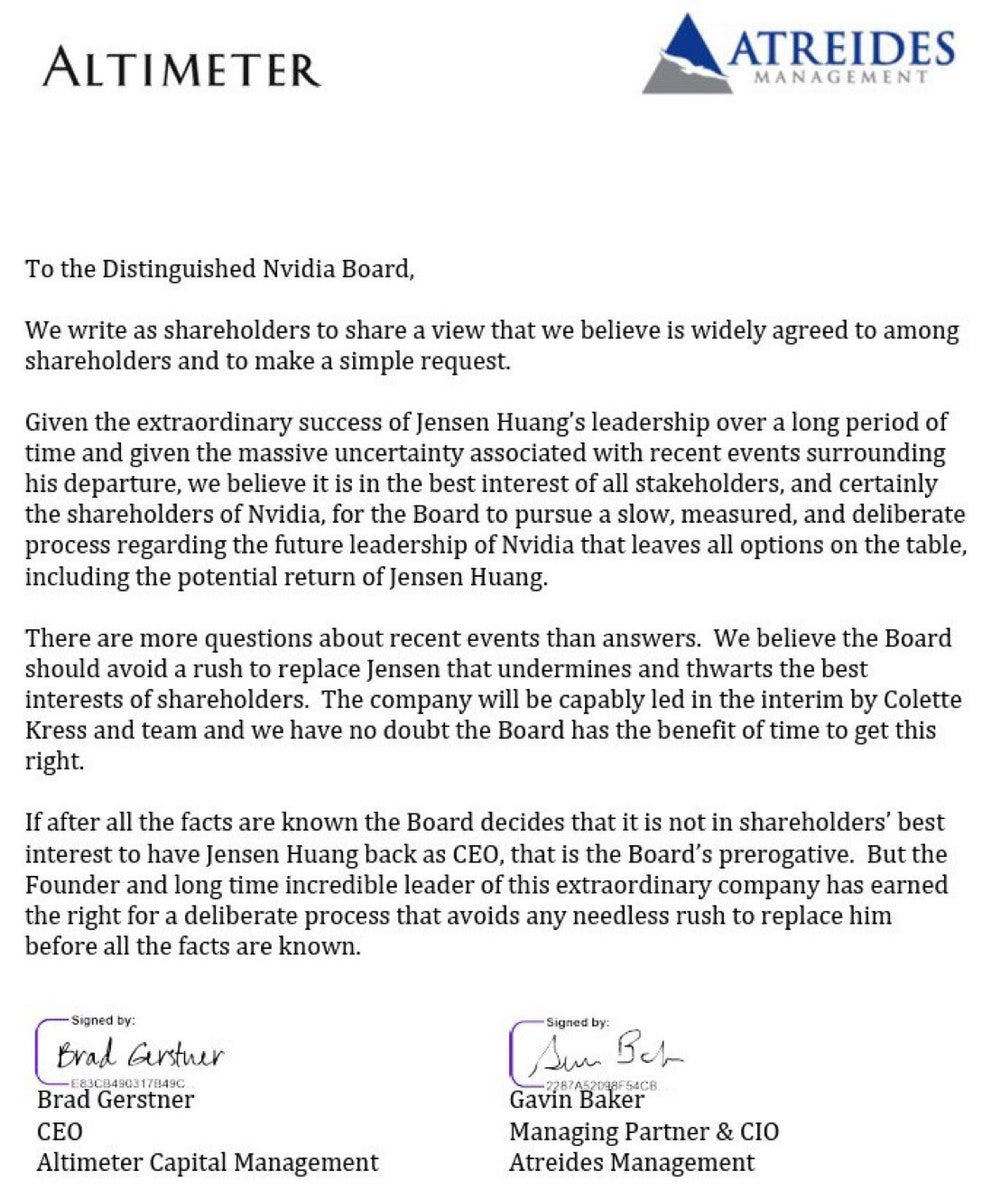
    The NVIDIA bulls are panicking, and the letter they sent the board on Friday proves it. With a federal investigation open into whether advanced American AI chips were smuggled into China, 2 of the loudest voices in the AI trade are lobbying to keep the door open for the man who was running NVIDIA the whole time. This is a national security issue, and every American should be furious about it. Silicon Valley has already told you how dangerous this technology is. Anthropic's IPO filing with the SEC warns that advanced AI could pose "catastrophic or existential risks to humanity," especially if it's misused or weaponized, and its CEO has put the odds that AI destroys humanity as high as 25%. NVIDIA's chips are what it takes to build those systems, so by the industry's own words, any of those chips ending up in China is a threat to every American. Brad Gerstner of Altimeter Capital and Gavin Baker of Atreides Management asked the board for a “slow, measured, and deliberate process” that keeps every option open, “including the potential return of Jensen Huang.” Gavin, Brad, are you out of your minds? Is protecting your position really more important than doing what’s right for this country? At the end of June, Altimeter held nearly $1.9 BILLION of NVIDIA stock, which made it the firm’s largest disclosed holding, and Atreides held nearly $250 million more. That’s $2.13 BILLION riding on this stock, so it’s easy to see who this letter is really looking out for. Huang resigned on Thursday after reports tied him to a woman U.S. intelligence believes was recruited by China’s Ministry of State Security. She used to run Megaspeed, a Singapore company that bought billions of dollars of NVIDIA hardware, and the Justice Department is investigating Megaspeed over potential violations of U.S. export rules on advanced AI chips. NVIDIA denies any part in illegal chip transfers and its board says it has no reason to believe national security was compromised, but the investigation isn’t finished, and these 2 still decided this was the moment to lobby for his return. The whole AI cycle has run on promotion. Silicon Valley’s biggest promoters pump the tulip bulbs so everyday investors will buy them at the top, and that’s how the insiders get their exit liquidity. Exit liquidity means someone has to be on the other side of the trade when the smart money sells, and they’d like that someone to be you. What should scare the bulls even more is the money behind all of this: Under Huang, NVIDIA became the bank of the AI boom. At the end of July, it held $98.9 BILLION of stakes in other companies, many of them its own customers, and in the first 6 months of this fiscal year it booked $23.7 BILLION of gains on those stakes. Some of that money went to neoclouds like CoreWeave, which turned around and bought more NVIDIA chips. I’m confident the interim CEO and the new board chair will be far more careful about handing out that kind of financing after this week, and with every chip distributor in Asia under a microscope, the demand that was quietly finding its way to China gets a lot harder to fill too. Once that money slows, I think the neoclouds start filing for bankruptcy, and NVIDIA’s revenue lands 30% to 40% short of what it would have been, with the growth rate falling apart right behind it. We’ve been short the neoclouds since June, and CoreWeave is down 50% since we called it. NVIDIA reports on Tuesday, and I expect AI stocks to get hit hard into year end, when the big money gets defensive and stops stepping up to take risk. This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
    • Transcript
  • November 13 · 1 hr 4 min

    Emergency break-in episode: Nvidia Is Enron 2.0

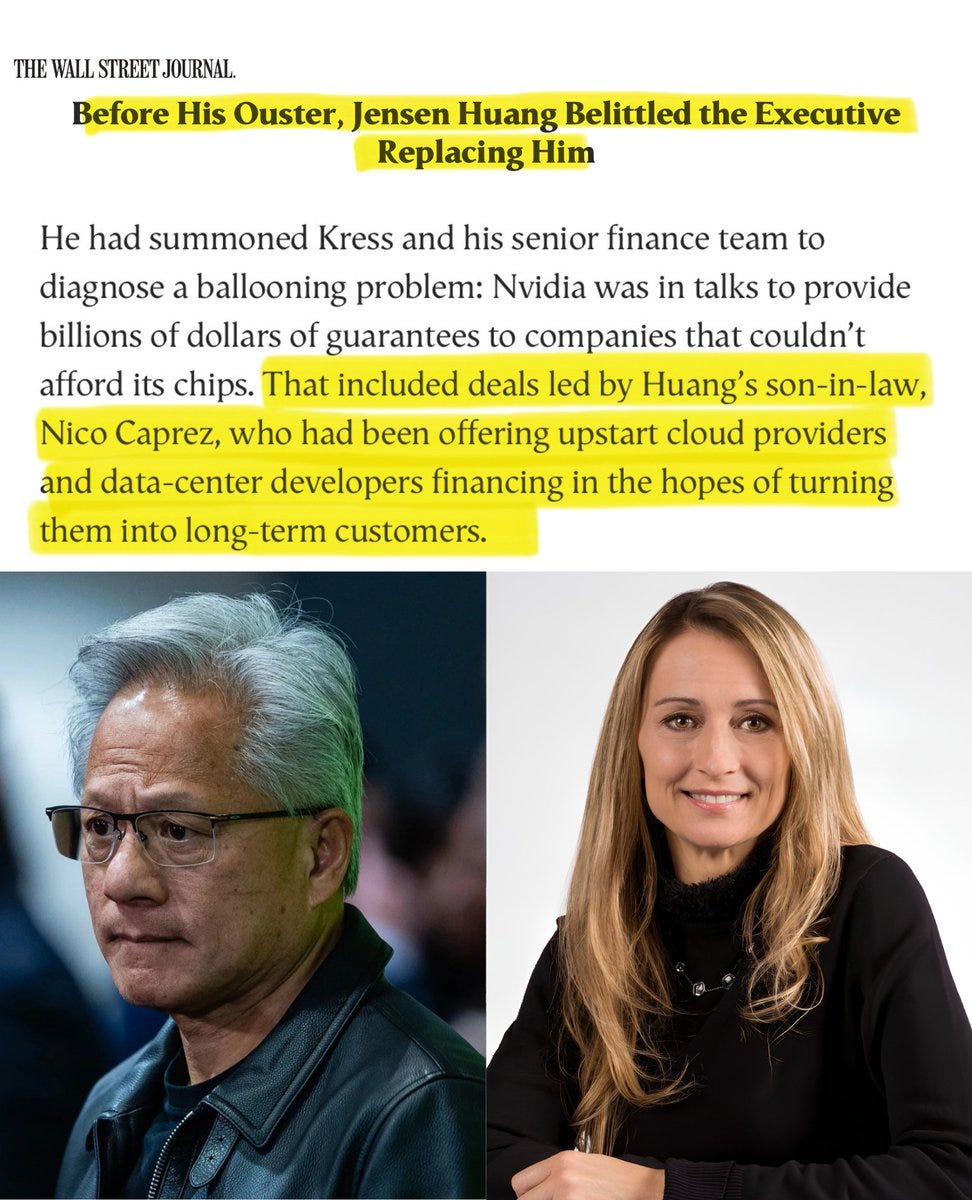
    Nvidia was the bank of the entire AI trade, and the bank is now closed. The MUST-READ report below shows how Nvidia kept the music playing. It handed out billions in financial guarantees to AI companies that couldn't afford its chips, so they'd keep buying them. Commitments and guarantees have exploded to $530B, up from $184B a quarter earlier, and that's almost 6 times the $91B of liabilities on its balance sheet. Nvidia plays investor, lender, supplier and backup customer in the same deal, so the money goes out the front door and comes back as sales. Jack Gamble (Nobody Special) and I went through all of it in an emergency episode, and I didn't hold anything back. This has a real Enron vibe to it. My friend Jim Chanos calls self-dealing vendor financing like this legal fraud, since it technically violates no laws and in substance is fraudulent. When the bank of AI closes, the heart stops pumping blood and the whole system dies with it. Colette Kress, the CFO who questioned these deals, now has to open the books completely, because anyone who fails to clean house on their watch owns the mess. Nvidia reports on Tuesday, and the Anthropic IPO lands 2 days later. Jack brought all the receipts: * A report of $200B in GPUs sitting dark in warehouses * CoreWeave's net loss up 544%, with adjusted EBITDA that strips out interest, depreciation and $2.5B of stock compensation on a company that rents GPUs * IPOs from Firmus, nScale and SB Energy flopping or delayed since early October, plus a $3.7B loss at SoftBank I think the entire AI structure is at risk: semiconductor stocks back to book value, neoclouds out of business, and a sector that makes up 40% of the equity market dragging everything else down with it. My advice is to protect your capital first. Avoid tech, get out of the index funds that are loaded with it (which is exactly what your wealth manager doesn't want you to do), and keep dry powder for what comes after. We are also DOUBLING DOWN on our NVIDIA short today! Don't be the exit liquidity. This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
  • November 9 · 5 min

    $10 Billion Bets on a Tech Bottom. I’m Not Buying It.

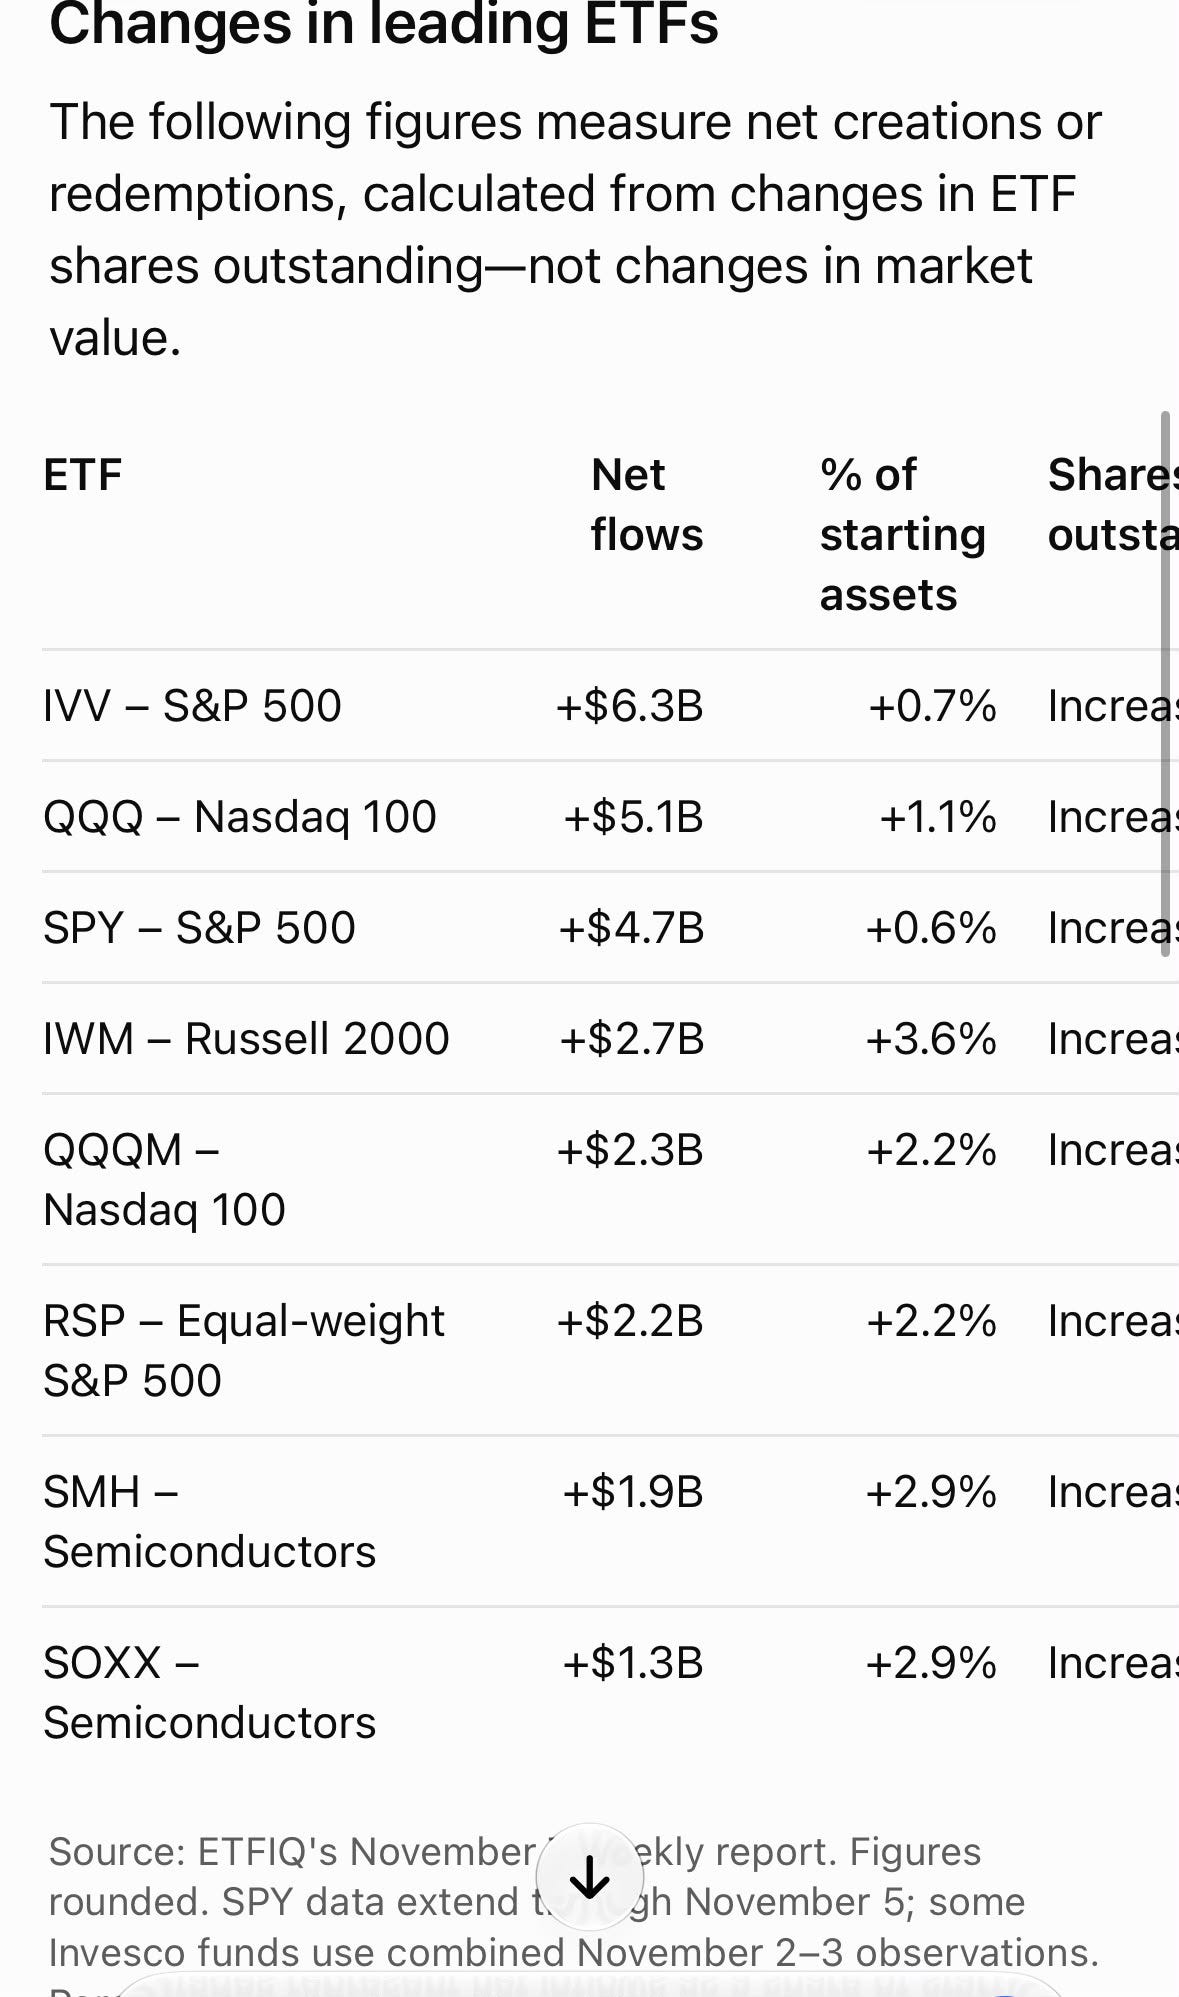
    More than $10B poured into Nasdaq 100 and semiconductor ETFs in a single week, right into a falling tech market. If you're a bull, that's the LAST thing you want to see. Bottoms form when people finally give up, and this crowd is still buying every dip with both hands. Now add the calendar: it's November, and a fund manager who's behind for the year isn't going to stand up and take more risk, so every leg down invites MORE selling. And for the AI names, it gets worse… Their stock price is their cost of capital, and it's rising at the exact moment they need more money. Tech is in a bear market, and in a bear market you're either short or flat. We positioned for this early, and we're keeping our foot on the gas. We have big news coming about The Noble Update in the next couple of days, so if you've been on the fence, now's the time to subscribe. This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
    • Transcript
  • November 6 · 3 min

    Emergency Subscriber Call Replay (with Michael Howell, David Trainer, Michael Kramer, and MORE)

    This is a free preview of a paid episode. To hear more, visit georgenoble.substack.com If you missed last night’s emergency subscriber call, you missed a lot. The room stayed packed to the very end of a 70 minute session with Michael Howell, David Trainer, Frank Longman, Michael Kramer and Nobody Special, and the conversation was on fire from the first minute. We talked about: * Where we are in the liquidity cycle, and what to own while it dra…

  • November 5 · 1 hr 27 min

    The Ultimate AI Debate

    Before you watch: We're hosting an EMERGENCY subscriber call tonight at 7:30 PM ET. The AI trade is coming apart in real time, and I'm going live with Noble Update subscribers tonight to walk through exactly where I stand. The Zoom meeting details: AI is a wonderful product and a lousy investment, and I went toe to toe with Gene Munster of Deepwater on exactly that in a debate on ZeroHedge. Gene thinks we're in the third inning and called this a buy opportunity. I think the internet already showed us how this ends. The bulls of 1999 were right about the internet, and anyone who owned Nortel, Lucent or Global Crossing still got wiped out. If the payoff on AI were so obvious, the market would hand these companies the money freely. Instead Nvidia has to play the bank of AI and back its own customers so they can keep buying its chips. It's a commodity, the Chinese are doing it for 95% less, and the bond market is already sending the bill. This was a fun debate, and the bulls have nothing left but copium. This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
  • November 4 · 39 min

    The Final Cash Out

    Wall Street tried to sell WeWork to the public at $45 billion, and weeks after the IPO fell apart, SoftBank put it on its own books at $4 billion. My friend David Trainer of New Constructs was one of the first to call out WeWork, and he thinks Anthropic is the same movie with a much bigger ending. He calls it the final cash out, and we went through exactly how it works: * How your index fund, pension and 401k end up holding the bag * The $900 billion of purchase commitments, roughly 45 times revenue * The vendor costs Anthropic wants kept out of its earnings * The red flag its own auditors raised on internal controls * The shares insiders can sell within days of the IPO The crash will be EPIC, and David cuts through the noise in this one. Follow David Trainer on X: x.com/theRealD This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
  • November 3 · 4 min

    Replay for the Noble Update Zoom Call (with Peter Boockvar)

    This is a free preview of a paid episode. To hear more, visit georgenoble.substack.com Our subscriber call last night was TERRIFIC. The election is today, and I told subscribers exactly how I'm positioned for what comes after it. My friend Peter Boockvar joined us too. We talked about: * Why $200 oil is on the table, even if the war ends * What I expect from the market once the election is behind us * The simplest way I know to own uranium * What to ch…

    • Transcript
  • November 2 · 1 min

    Don’t be their exit liquidity

    The tech bros are lining YOU up to be their exit liquidity, and the Anthropic IPO is how they plan to do it. Anthropic just disclosed $895B in spending commitments ahead of its IPO, and Robinhood is already fighting for a piece of the shares Anthropic may set aside for retail investors. When the people who got in early want the public holding the bag, you should be angry, very angry. I'll go through all of it tonight on our subscriber call at 7:30 PM EST, along with the process behind our 70% long/short spread. The Zoom details are in the post below: This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
    • Transcript
  • October 30 · 2 min

    The S&P 500 went NOWHERE in October

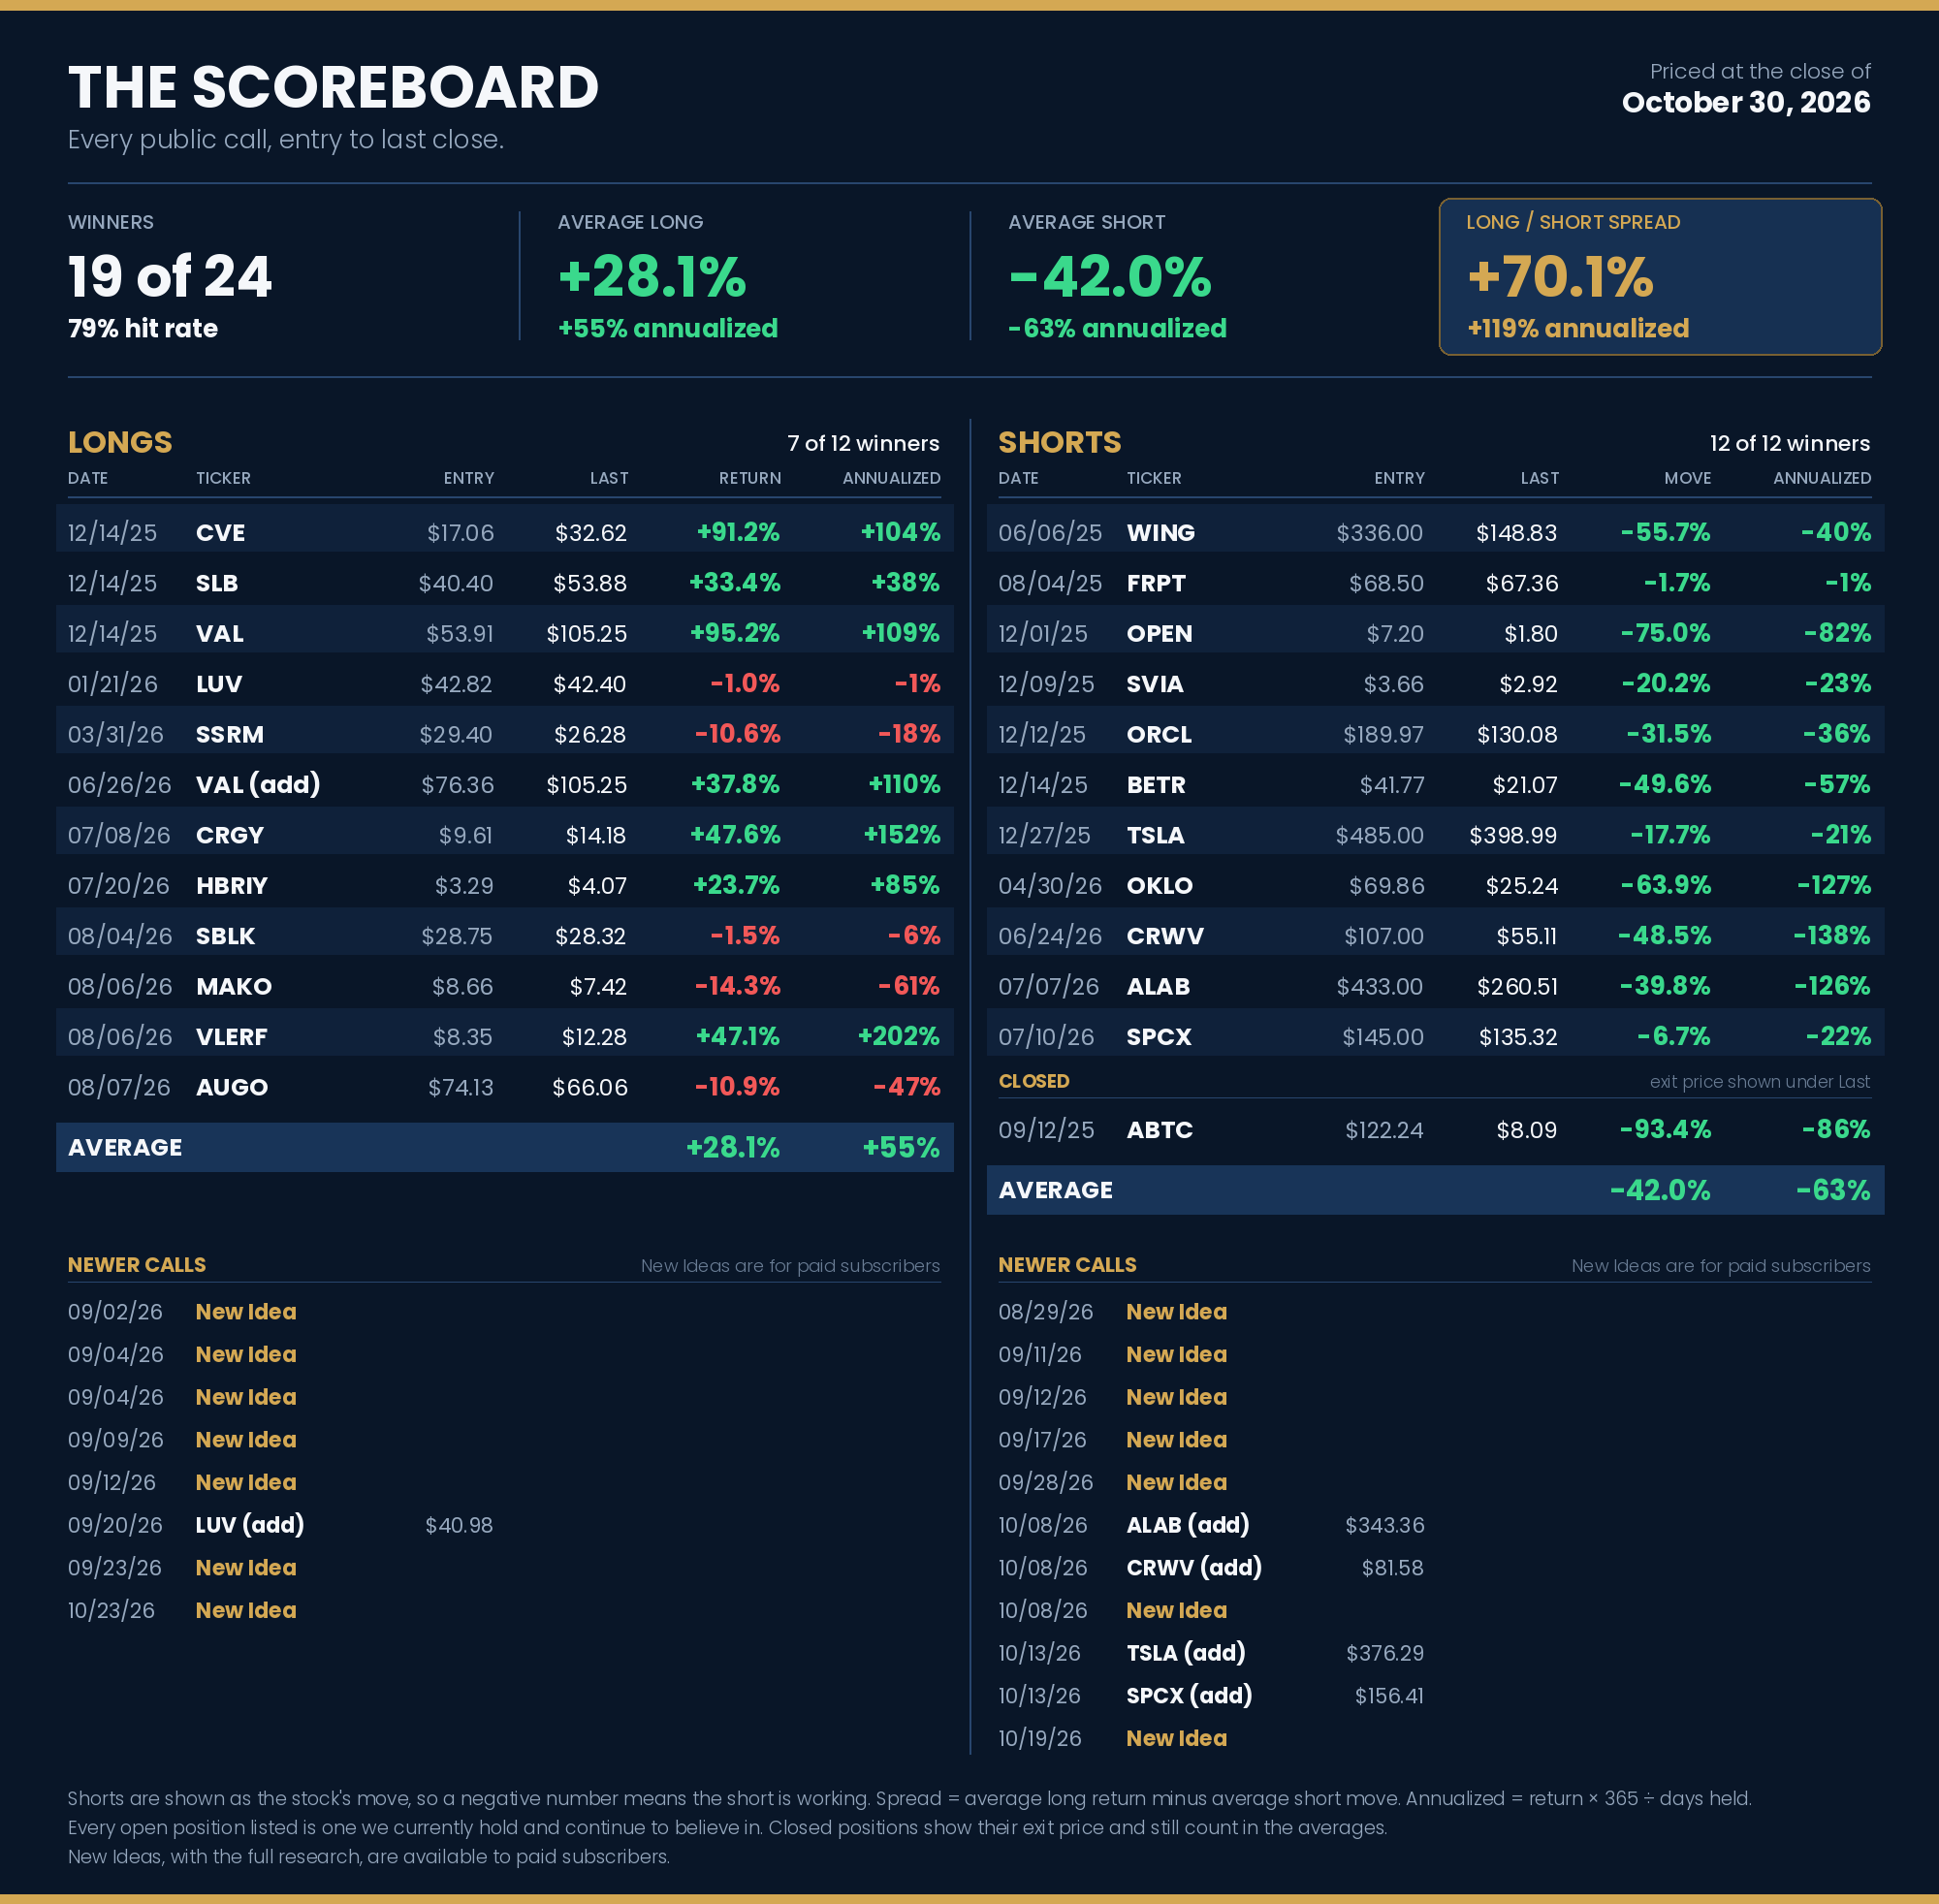
    Energy was up 11.8% and tech was down 2.7% through Thursday, and we were long energy and short tech the whole time. Our long/short spread is now 70.1% (119% annualized), and all 12 of our scored shorts are winners. If all you owned was the index, you got a flat month and MISSED every bit of it. The tide is going out. Money isn’t cheap anymore, so valuation and fundamentals matter again, and the stocks priced on stories are the first to go. I think the tech rout is just getting started. On Sunday at 10 AM ET I’m going live with Noble Update subscribers to go through the portfolio and our process, and to explain why I think SpaceX is about to crash - instructions to join are below and replays will be available: If you missed this week’s Best Technical Ideas Summit, the replay with all 60 ideas is up here: noble-capevents.com/btios-watch-the-replays The Noble Update is the #1 place for alpha. I want you to MAKE MONEY. This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
    • Transcript
  • October 23 · 47 min

    The Most Hated Sector Is Where the Value Is

    All it takes to break the AI picks and shovels trade is order growth slowing from 30% to 15%. That's STILL double-digit growth, but the stocks can get crushed anyway. My friend Peter Boockvar joined me, and he thinks this is gut check time for the whole trade: * The warning lights already flashing on the AI dashboard, from Chinese chipmakers to scrapped data center IPOs * Why the memory chip boom peaked within weeks of a Chinese rival going public * The credit market pricing a 55% chance that one AI darling defaults within 5 years * The cyclical chip stock that just became the top holding in a major value ETF, and why that should worry you * The most hated sector in the market that Peter loves right now You can also watch the full conversation on Youtube: This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
  • October 22 · 13 min

    The bond market just started calling the AI trade's bluff

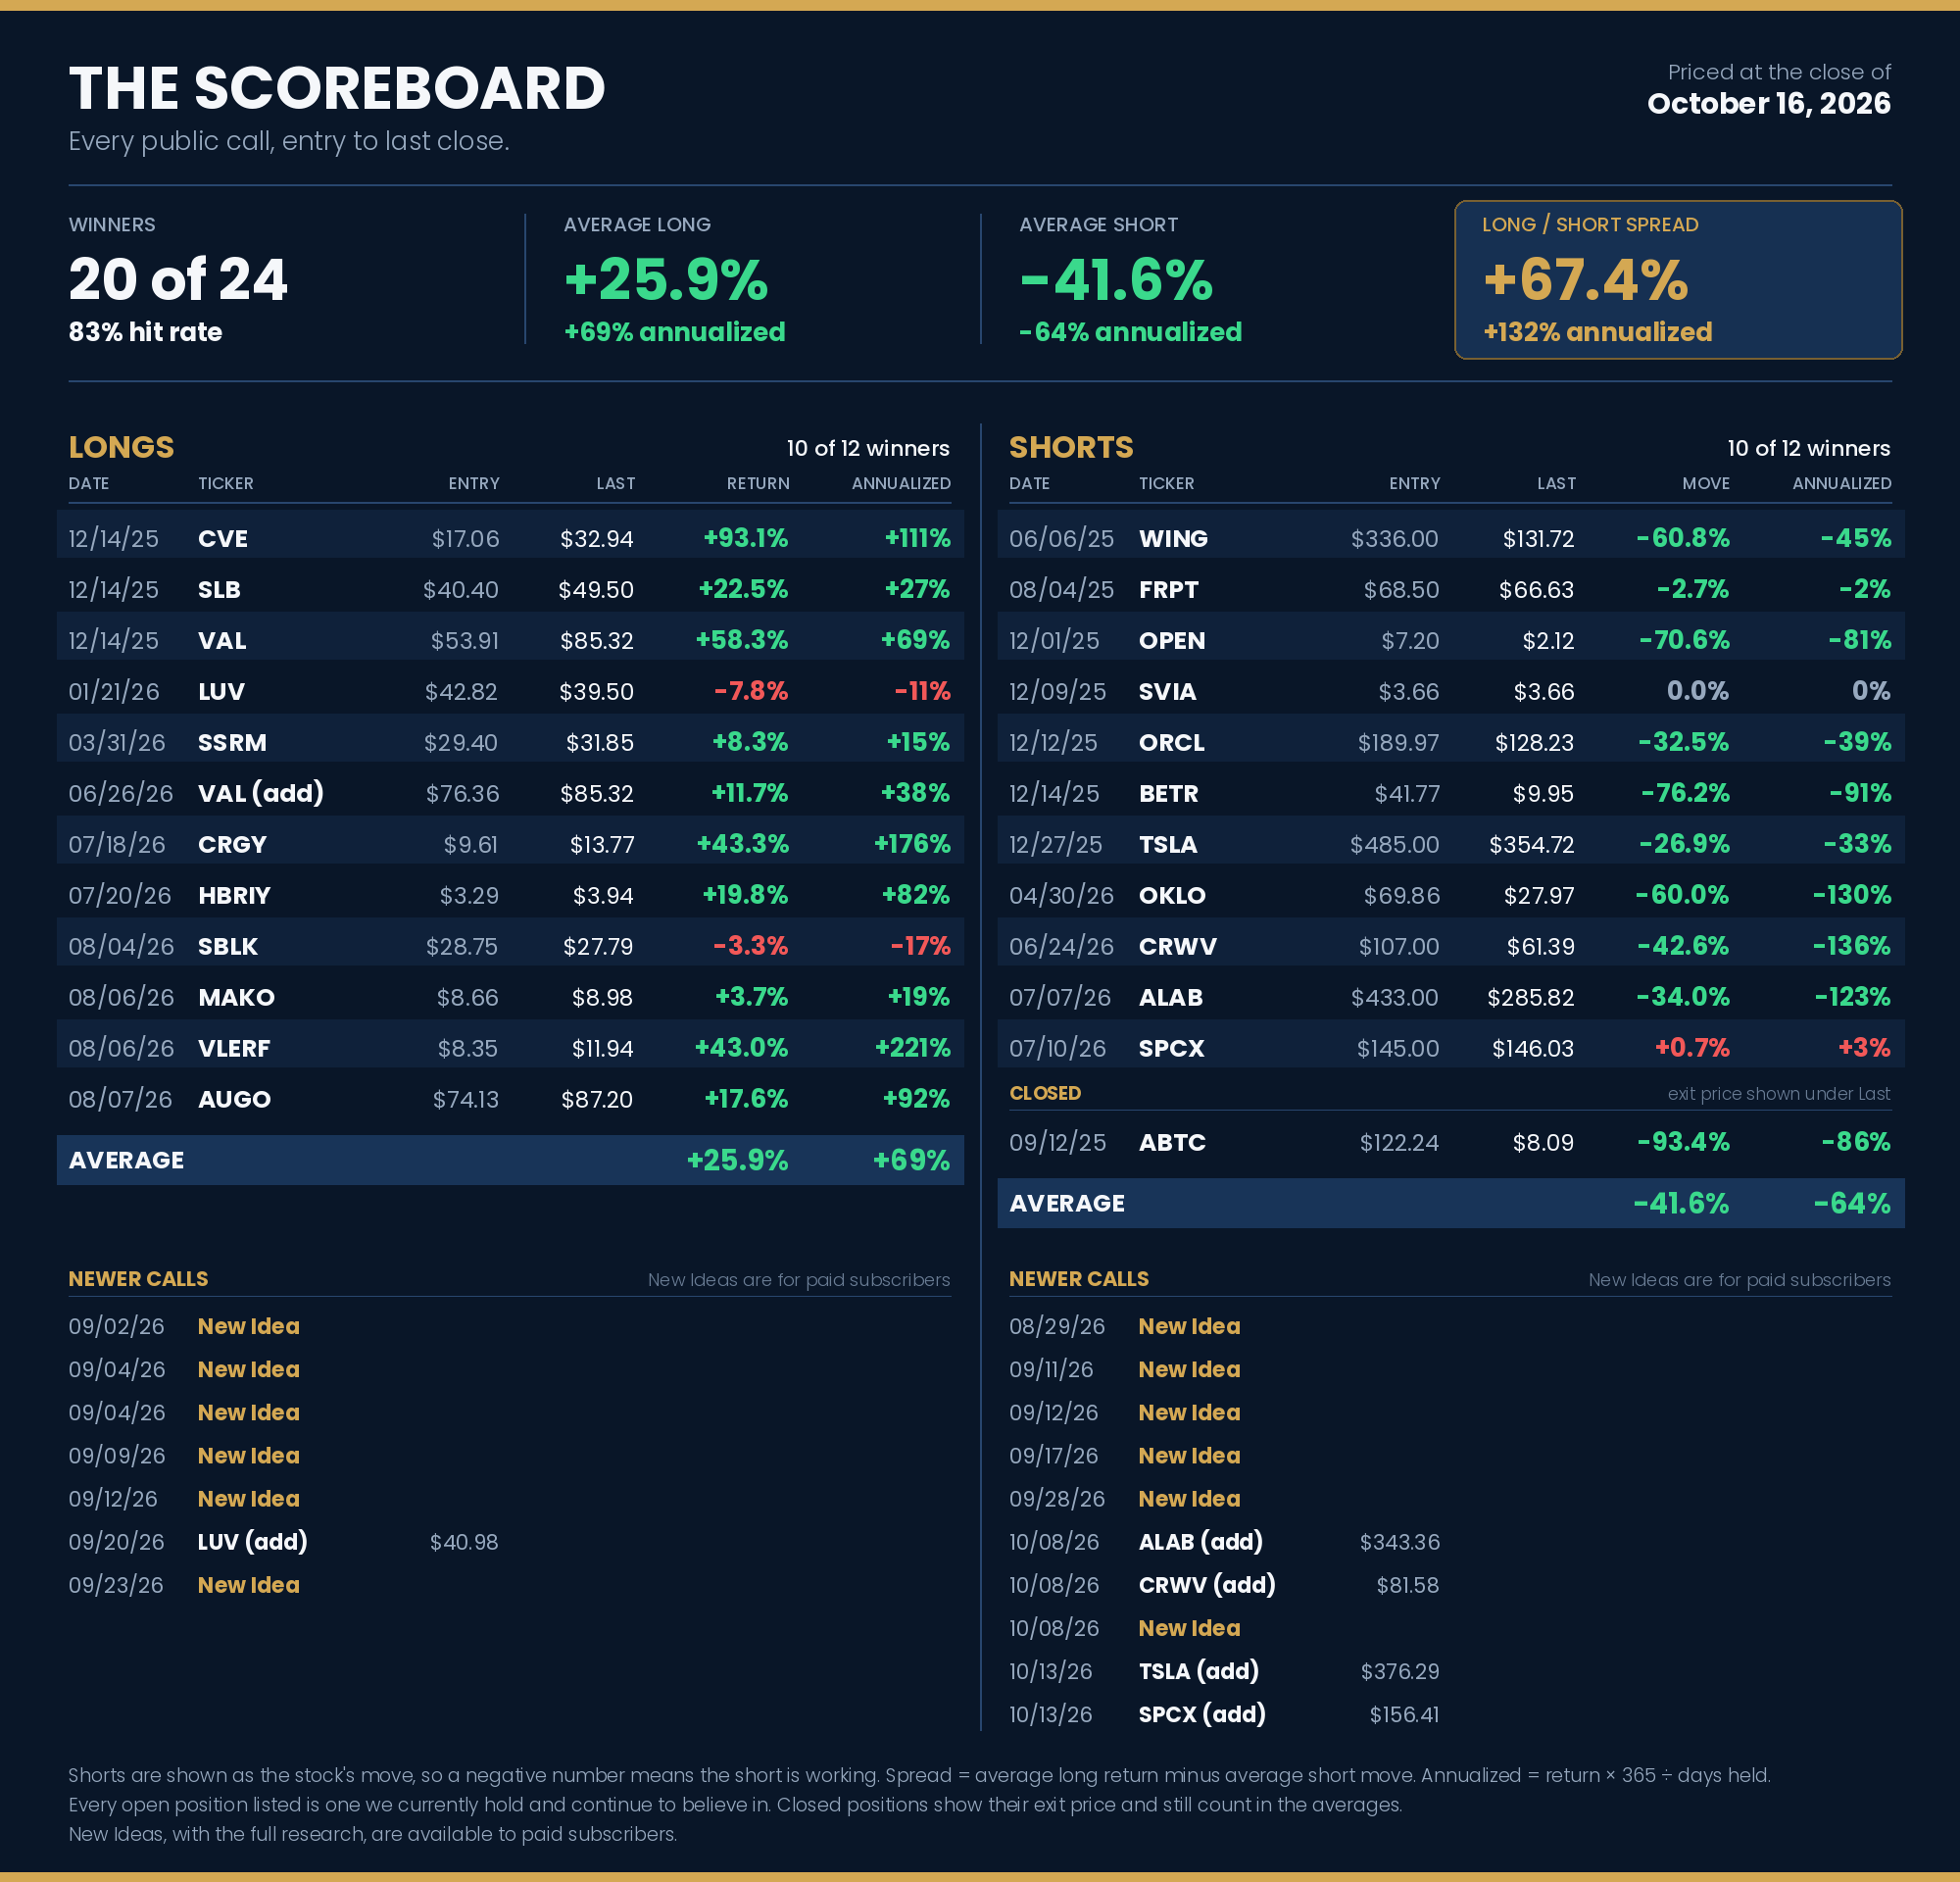
    Last week CoreWeave's bonds traded at yields around 15%, and the cost of insuring its debt implied roughly a 60% chance of default within 5 years. Oracle's default insurance hit a record high at the same time. That's what it looks like when narratives and dreams run into a lack of cash flow and a mountain of debt. When easy money dries up, the most indebted company with the weakest fundamentals gets shot first, which is why CoreWeave is at the front of the line. It's our biggest short, we added to it 2 weeks ago, and I think it's a better short at around $60 than it was at $107. As Hemingway put it, you go bankrupt gradually, then suddenly. Check out the full conversation. Sign up for The Best Technical Ideas Online Summit here: noble-capevents.com P.S. Every position we hold is on our public scoreboard with the date and price we called it, including the ones that aren't working: This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
    • Transcript
  • October 21 · 56 min

    The Insurance Reckoning with Tom Gober

    This is the final episode of our series with Tom Gober. Last episode ended with Tom challenging the offshore reinsurers to show us the $1.5 trillion, and in Episode 4, he shows you which companies are behind it. Just 40 companies account for 85% of it, and the biggest sends $235.7 billion to a single offshore affiliate while holding only $4 billion of surplus, which Tom describes as moving money from one pocket to another, like "trust me, bro, I got this." Here's what we're going over in Episode 4 "The Offshore Black Box": * Tom maps every internal reinsurance deal at a household name in American insurance, with billions swirling between its own companies and all of it tapping into 7 captives in Arizona where you can't get any information. * Tom shows how a company you'd recognize asked Texas to approve a reinsurance deal worth more than $20 billion with its own affiliate, and when it never heard back, it disclosed the deal as "non-disallowed." * Tom ranks the 25 carriers he worries about most, and at the top of the list, just over 1% of the higher-risk assets going bad would wipe out the entire surplus. * Tom shows that over the last 9 years, the industry's surplus grew by about 50% while the affiliated reinsurance he's worried about doubled. We also call out 9 state insurance commissioners by name, so stay for that. I'm very bearish on private equity and private credit, and this episode made me even more so. Insurance companies have been a huge source of money for those firms, and a lot of that paper ended up in 401(k)s and pension plans, so a firefighter in Peoria who's never thought about private credit may already own it. Over 4 episodes, Tom has taken us from a recorder hidden in a briefcase to a $1.5 trillion question the regulators still haven't answered, and neither of us got paid a cent to do it. We did it because the people who've paid their premiums on time for years deserve to know where their money went. I'm asking every American who watches this to speak up, and the easiest place to start is sending this series to anyone you know with a life insurance policy or an annuity. Tom's closing words say it all: The more people who hear the truth, the better off the policyholders will be. This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
  • October 17 · 31 min

    The Insurance Reckoning with Tom Gober

    Last episode, we left off with Tom Gober about to reveal a secret document he found in a company president’s personal files, and Episode 3 opens with what it said. A CFO in a criminal case was recorded calling these offshore deals “a little bit like morphine,” and Tom explains why: once you start, the hole gets bigger and you need a bigger dose. Here’s what we’re going over in Episode 3 “The Secret Side Letter”: * Tom tells you what was in the side letter hidden behind a reinsurance contract that looked perfect to an examiner, from a case that sent the man in control to prison for 18 and a half years, and you’ll hear what happened when the FBI knocked on his door in Del Mar. * Tom puts the cushion of the entire US life and annuity industry at about $650 billion, and he says more than that sits in secret captives alone, while more than $1 trillion has gone offshore, out of sight. * Tom shows what happened at a big insurance group after KKR took it over from Goldman Sachs, including a carrier with about $3.7 billion in affiliated investments sitting on roughly $200 million of surplus, where a 6% haircut would wipe out its entire surplus. * Big institutions hold more than $500 billion of short-term notes issued through these insurers, and at one of those companies, a legal opinion puts those investors on equal footing with policyholders like you, which Tom says means they’ll see trouble coming first and get to the exit before you do. Tom also names the two insurers he loves, so stay for that. In my world, if you sell a stock through one broker and buy it right back through another, that’s painting the tape, and you’re not allowed to do it because it kills true price discovery. When the same owner sits on both sides of an insurance company’s investments, it looks eerily similar to me. Tom ends this one with a simple message for the offshore reinsurers and secret captives: if the $1.5 trillion is really there, show us. This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
  • October 16 · 6 min

    The era of easy money is over, and the market made that very clear today.

    Our long/short spread widened to 67.4% today, with our longs up 25.9% on average and our shorts down 41.6%. This post has bonus content for paid subscribers. Upgrade to get full access. We made money on both sides of the book, which is exactly what a hedge fund is supposed to do. But the people chasing momentum and narratives are having a very different day. When the tide of easy liquidity goes out, the momentum and narrative bros find out what they really own, and anyone who's been doing the work on valuation and fundamentals finds this market pretty easy to read. We doubled down on a lot of our shorts last week, and CoreWeave alone is down almost 25% since we added to it on October 8. If you only started investing after the financial crisis, all you've ever known is more liquidity, and that game is OVER. I'm not calling a crash, because we're long and short, but the downside from here looks much bigger than the upside, and I have far more conviction in my shorts than my longs. If you want 60 more ideas for what comes next, our technicians conference runs October 27 and 28, with 20 of the best chartists on the street bringing 3 ideas each. Tickets are $99 until midnight tonight, and then the price goes to $199. noble-capevents.com BRACE FOR IMPACT This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
    • Transcript
  • October 16 · 2 min

    LAST CHANCE: The investment event of the year doubles in price tomorrow

    Today is the last day you can get into the Best Technical Ideas Online Summit for $99, and I couldn’t be MORE EXCITED about this one. I like to say that putting on these summits is like coaching an All-American team. Most conferences are stuck with whoever’s on their roster, while we get to pick the best players in the country. On October 27 and 28, that team is John Roque, Rich Ross, David Keller, Brian Shannon and 16 more of the best technicians on Wall Street, and I’m hosting the summit in collaboration with Bill Kelleher. Each speaker brings 3 ideas, so you walk away with 60 of them over 2 days. It runs 10 AM to 4 PM ET with replays if you can’t watch live, and every session goes straight to the charts with no fireside chats and no bloviation. The focus is ACTIONABLE, MONEY-MAKING IDEAS. Back in the day, hedge fund guys would get together for stock idea dinners where the price of admission was an idea, and you walked out with a notebook full of them. This summit brings that experience to the individual investor, and that’s what democratizing finance the right way looks like. I wish I’d had access to something like this when I was starting out at Fidelity 45 years ago. Conferences with this kind of firepower cost thousands of dollars to attend. You can’t even buy a good dinner for $99, and today that’s the price of 60 ideas from the best chart readers in the business. If you’re wondering why you should care what technicians have to say: This market runs on narrative dominance, and the chart is where you see what the money is really doing. If you're not willing to spend $99 to hear what these 20 people see in the charts, are you really serious about your money? The early bird price ends today, and tomorrow the ticket goes to $199. Lock in your seat for the investment event of the year here: noble-capevents.com It’s a market of stocks. This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
    • Transcript
  • October 15 · 42 min

    The Emperor Has No Clothes: Oil, AI & What Breaks Next

    1. Strategic Actions and Decisions * Maintain a heavy 50% allocation to energy trades: The risk of escalation remains elevated, physical inventories are depleted, and supply continues to lag behind demand. * Re-evaluate Petrobras (PBR) as a buy following political re-rating: The stock offers upside toward $30–$35 due to favorable election runoff dynamics, capital rotation, and strong underlying fundamentals despite past governance discounts. * Capitalize on Methanex (MEOH) undervaluation: Take advantage of severe global supply constraints resulting from blocked Iranian methanol exports and low US feedstock gas costs, which set up a strong upside re-rating. * Trim gains in tanker equities: Reduce exposure as duration risks grow and substantial new vessel deliveries enter the market around 2027. * Hedge against rising 10-year Treasury yields: Prepare for equity market volatility following the election, as higher cost of capital impacts debt-financed sectors and corporate earnings. Executive Summary Energy markets remain structurally tight due to depleted inventories, impaired flows, and ongoing geopolitical friction in the Strait of Hormuz. Despite short-term price fluctuations, deferred long-term oil futures continue to rise, strengthening cash flow valuations for producers. Petrobras and Methanex represent asymmetric long opportunities driven by political developments and supply disruptions, respectively. Conversely, caution is warranted in semiconductor equities and debt-dependent growth sectors due to overcapacity risks and surging Treasury yields. Investors should prepare for potential equity market friction post-election as corporate earnings digest higher capital costs. Key Takeaways and Practical Lessons * Long-Term Futures Drive Energy Equities: Equity valuations depend more on the deferred futures curve than spot prices; sustained $80–$90 oil over several years creates durable, higher-rated cash flows. * Focus on long-dated strip pricing rather than daily spot volatility when valuing energy producers. * Political Catalysts Can Remove Governance Discounts: Emerging market state-backed equities can experience rapid capital re-allocations when election outcomes favor fiscal stability and market-friendly policies. * Reassess undervalued state-backed assets when domestic policy shifts de-risk structural governance penalties. * Inelastic Chemical Commodities Present Asymmetric upside: Physical commodities like methanol without strategic reserves experience rapid price spikes when major global supply nodes face sanctions or disruptions. * Identify global supply bottlenecks in non-storable industrial inputs to trade commodity-linked producers before quarterly earnings reflect higher realizations. * Cyclical Capital Expenditure Traps Threaten Growth Sectors: Mass capital expenditure in capital-intensive industries like semiconductors inevitably leads to oversupply and margin compression when demand softens. * Avoid buying cyclical technology equities at peak earnings multiples driven by debt-fueled capital expenditure booms. * Macro Yield Pressures Eventually Impact Equity Earnings: Delayed macroeconomic impacts from high interest rates inevitably manifest during quarterly earnings, even if short-term equity markets appear resilient. * Stress-test equity portfolios against sustained 6% borrowing costs and elevated Treasury yields. Follow Sam Kovacs🔗 Website: https://sam-kovacs.com/🐦 Twitter/X: @SamKovXSubstack: @samkovacs Watch on Youtube This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
    • Transcript
  • October 14 · 1 hr 2 min

    Stocks Could Go Nowhere While Inflation Eats Your Money

    Grab your seat for The Best Technical Ideas Online Summit at $99 before the early bird doubles to $199 on Friday: noble-capevents.com 1. Strategic Actions and Decisions * Re-evaluate long-term bond exposure: Shift positioning away from long Treasury holdings as persistent global capital demands and rising inflation expectations push yields significantly higher. * Capitalize on French and European fiscal shifts: Monitor European political realignment and fiscal commitments, such as Le Pen’s proposed debt break, for opportunistic bond and currency positioning. * Assess AI tech ecosystem exposure: Monitor top hyperscaler capital expenditure levels and SpaceX or SoftBank market signals to identify the turning point in the tech infrastructure cycle. * Reallocate capital from US equities to Japanese equities: Underweight broad US equities facing compressed valuation multiples while going long Japanese equities supported by structural loan growth and non-inflated real estate. * Divest from traditional oil and energy assets: Reduce structural exposure to crude oil as rising EV adoption in major markets like China structurally breaks the historical link between GDP growth and oil demand. Executive Summary Global capital markets face a fundamental regime change defined by a rising cost of capital, structural inflation, and fiscal expansion. Driven by an aggressive capital war in AI infrastructure and persistent government spending, interest rates are poised to remain higher for longer, rendering standard backward-looking portfolio models obsolete. Broad US equities appear historically overvalued against bond yields, while Japanese equities present compelling upside due to structural bank lending growth. Furthermore, oil demand faces structural decline from EV adoption, whereas gold remains a critical physical hedge against central bank treasury freezes and fiat debasement. Key Takeaways and Practical Lessons * Rising cost of capital is driven by structural capital demand, not just central bank policy: Aggressive corporate spending in AI and persistent government fiscal deficits are sucking up global liquidity and driving up borrowing costs across all sectors. * Practical Lesson: Audit debt structures and avoid relying on past low-rate refinancing assumptions; prepare balance sheets for sustained high borrowing costs. * The traditional debasement trade requires active relative hedging: Holding gold without hedging against bond yield movements creates significant drag when central banks refrain from capping yields. * Practical Lesson: Pair long precious metals allocations with short long-dated government bond positions to hedge against un-capped yield expansion. * Japan is undergoing a structural economic regime shift: Decades of balance sheet deleveraging have ended, replaced by positive loan growth, foreign direct investment, and unconstrained real estate capacity. * Practical Lesson: Rotate international equity allocations away from expensive US broad market indices toward undervalued Japanese equities and banking sector assets. * Technological disruption and EV adoption have broken the oil-GDP link: Road transportation energy demand is decoupling from economic growth, converting crude oil into a structurally weak asset over the long term. * Practical Lesson: Exclude traditional crude oil from long-term secular growth portfolios and reallocate toward renewable energy infrastructure and physical gold. * Financial indicators like CDS spreads no longer reliably signal equity distress: Massive liquidity structural shifts have decoupled corporate credit default swap pricing from underlying equity valuations. * Practical Lesson: Rely on corporate capital expenditure peaks and primary funding stress rather than traditional CDS metrics when timing short positions. Follow Russell on Substack → https://www.russell-clark.com Watch on Youtube: This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
  • October 14 · 5 min

    2 DAYS LEFT: Wall Street's best technicians present their 60 best ideas for $99

    20 of the best technicians on Wall Street are bringing you 60 ideas, and the $99 price ends Friday. On October 27 and 28, John Roque, Rich Ross, David Keller, Brian Shannon and 16 more will each present their best ideas at the Best Technical Ideas Online Summit, which I'm hosting in collaboration with my friend Bill Kelleher. It runs 10 AM to 4 PM ET both days, and the replays are available if you can't watch live. Thousands have attended these summits, and I think this one is going to be our best yet. Even at $199 this would be a steal, but you can still lock in $99 until Friday: noble-capevents.com Our own calls are running hot too: the spread between our longs and our shorts is 63%, and that's before you annualize it. That's the kind of alpha we chase, and it's exactly what these 20 technicians bring to the table. This is our kind of market. Dispersion is huge right now, with money to be made on both the long side and the short side, and that leaves plenty of great pitches to hit. I couldn't be more excited about what I see coming. I cover what's happening in the market in the full video, so give it a watch! This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
    • Transcript
  • October 13 · 45 min

    The Insurance Reckoning with Tom Gober

    Last week we showed you the $2 trillion time bomb sitting inside America's life insurance companies, and in Episode 2 of our series with Tom Gober, we start naming names. Tom calls it the cash cow: premiums pour into an insurance company 365 days a year, and when a private equity owner sits on both sides of the table, he can steer that money into his own businesses while the policyholders pay him a fee for the privilege. Here's what we're going over in Episode 2 “Sports Empires & the Liquidity Trap” of The Insurance Reckoning with Tom Gober: * The billionaire who owns the Dodgers is under a federal criminal investigation in New York, and Tom shows how his insurers ended up with roughly 400% of their surplus in his own paper when the NAIC suggests a cap of 50%. * Tom called out this exact scheme back in 2014 as the expert on a complaint that exposed a straw man buying the reinsurer so it wouldn't look affiliated, and the case settled almost immediately. In the 12 years since, none of the state regulators raised it, and it took a federal prosecutor in a criminal case to bring it back up. * South Carolina just moved to put 2 companies into receivership, and their private equity owner is the same group that sued its own rating agency to stop a downgrade. That group has 3 more carriers in Utah, and Tom says the exact same playbook is running at the other private equity controlled carriers. Since we filmed, Florida has suspended the life insurer's license in the state. * If your insurer moves its money to an affiliate offshore, you have no legal claim on it, and Tom puts the liabilities that have already left US life insurers for offshore reinsurers and secret captives at more than $1.6 trillion. I got angry in this one. I believe the zombie companies need to go bankrupt and the people running them need to go to jail, because not a single big bank CEO did time after 2008 and look at the mess we have now. I also made a promise on camera to every state insurance regulator in America, and I intend to keep it. Figures don't lie, but liars figure. This is a public episode. If you'd like to discuss this with other subscribers or get access to bonus episodes, visit georgenoble.substack.com/subscribe
Showing 1–20 of 67 episodes